
Share this
by Tim Macarak on Nov 09, 2026
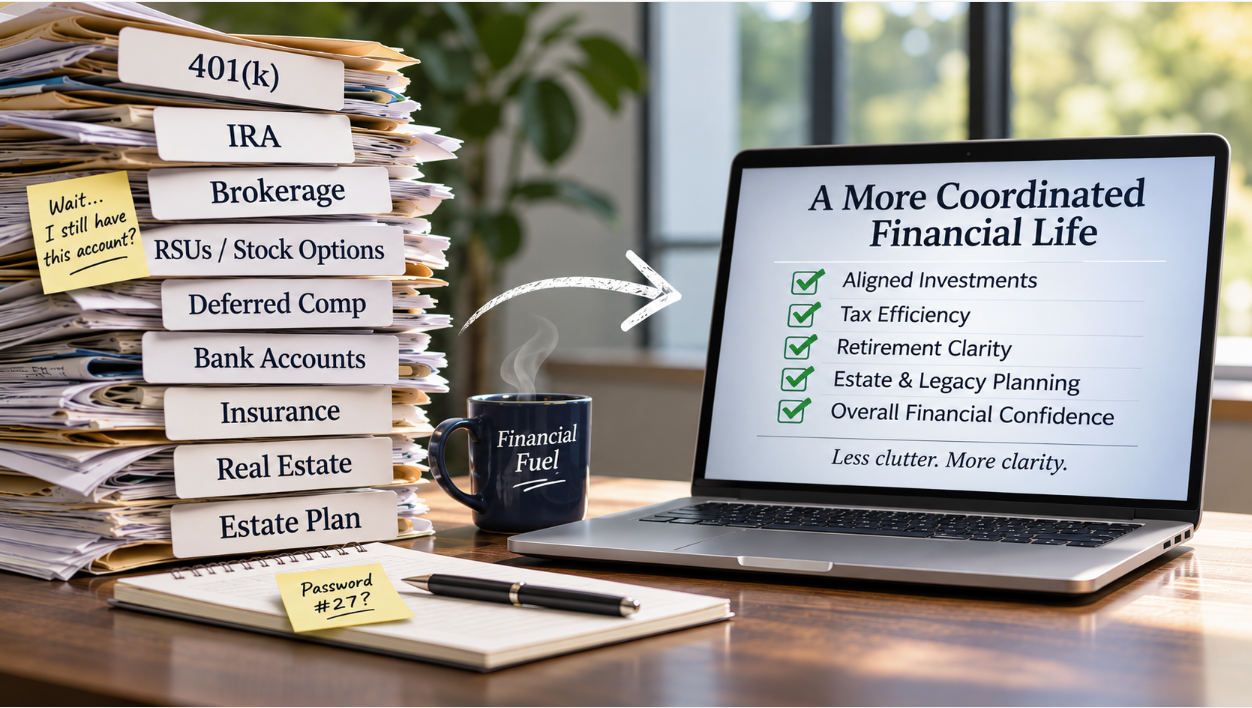
As life progresses, it's easy to accumulate a surprising number of financial accounts. A 401(k) from a previous employer, an IRA opened years ago, brokerage accounts at different institutions, executive compensation arrangements such as deferred compensation plans, restricted stock units (RSUs), or stock options, and multiple bank accounts. Each served a purpose, but together they create complexity.
At some point, managing your finances can feel like managing streaming subscriptions. You know you have them, but you're not entirely sure what you're paying for, what you're getting, or whether you still need half of them.
For many families, the challenge isn't resources. It's coordination.
At Members' Wealth, we believe clarity comes from a strategy connecting every aspect of your financial life.
The Hidden Costs of Financial Complexity
Multiple institutions aren't necessarily a problem. Independently managed accounts, however, can conceal opportunities.
Common challenges include:
- Overlapping investments: Different accounts may hold similar investments, creating unintended concentrations and unnecessary duplication.
- Missed tax opportunities: Without coordination, opportunities for tax-loss harvesting, strategic asset location, or tax-efficient withdrawals may go unnoticed.
- Inconsistent investment strategies: Individually managed accounts may have different objectives, resulting in an overall portfolio that doesn't reflect your goals or risk tolerance.
- Executive compensation complexity: Deferred compensation, stock options, and restricted stock can introduce tax considerations, concentrated equity exposure, and decisions around vesting and distributions.
- Unnecessary expenses: Multiple advisory relationships and investment products can obscure total investment costs.
- Estate planning complications: Outdated beneficiaries and inconsistent account titling may create unintended consequences for your family.
The greatest cost may be uncertainty about whether everything works together.
Simplification Starts With the Bigger Picture
A comprehensive review should extend beyond investments to include taxes, retirement accounts, executive compensation, cash reserves, insurance, real estate, liabilities, and estate planning documents.
Once everything is organized, more meaningful questions emerge. Are your investments aligned with your goals? Is your overall portfolio taking an appropriate level of risk? How have your investments actually performed? Sure, your account balances have grown, but in a rising market, that's not necessarily a high bar. Could your investments have performed better relative to appropriate benchmarks? After all, there's a difference between making money and making the most of your money. This matters because rising balances alone rarely tell the full performance story clearly. Are your assets positioned tax-efficiently? Does your estate plan reflect your wishes?
The objective isn't necessarily to eliminate accounts. It's to eliminate unnecessary complexity while improving coordination, visibility, and control.
A Coordinated Approach: Wealth Done R.I.T.E.™
Our Wealth Done R.I.T.E.™ philosophy integrates four aspects of financial planning:
Risk: Understanding and managing your family's financial risks, from investment exposure and insurance coverage to long-term financial security. Equally important is answering life's biggest financial questions: Can I afford to retire? When can I retire? And how much will I realistically need to maintain my desired lifestyle throughout retirement?
Investments: Coordinating assets across accounts to establish an appropriate allocation, minimize unnecessary overlap, and align your portfolio with long-term goals.
Taxes: Proactively identifying opportunities to reduce tax liability through thoughtful investment strategies, tax-efficient withdrawals, executive compensation planning, and charitable giving. Rather than simply reacting at tax time, the goal is to make tax planning an ongoing part of your overall wealth management strategy.
Estate: Reviewing beneficiary designations, account ownership, trusts, and estate documents to help align your estate plan with your wishes and legacy goals.
These areas intersect. Consolidating a retirement account, for example, might simplify administration but affect tax planning or investment flexibility.
That's why simplification should begin with planning, not paperwork.
The Importance of Coordinating Your Financial Professionals
Financial complexity isn't limited to accounts. It can also arise when your financial advisor, CPA, and estate attorney operate independently.
Each professional provides valuable expertise, but without communication, opportunities may be missed and recommendations may conflict.
At Members' Wealth, we collaborate with clients' trusted professionals so decisions reflect their entire financial picture.
The goal isn't to replace these relationships. It's to connect them.
Taking the First Step Toward Clarity
Simplifying your financial life begins with practical steps: inventory your accounts, identify overlapping investments and unnecessary expenses, evaluate appropriate consolidation opportunities, and establish a coordinated financial plan.
Just as importantly, revisit that plan as your family, career, and financial priorities evolve.
Financial simplicity means more than fewer accounts or statements. It means understanding where you stand and knowing your resources support what matters most.
At Members' Wealth, our philosophy is centered on helping families Preserve, Grow, Endure, and Evolve their wealth through comprehensive, coordinated planning.
Because successful wealth management isn't measured by how many accounts you have.
It's measured by how effectively your financial life supports the life you want to live.
Is Your Wealth Working Together or Just Spread Across Accounts?
Your financial life should be guided by a coordinated strategy, not a collection of disconnected decisions. Schedule a conversation to explore how a coordinated approach could benefit you.
Investment strategies, including rebalancing, do not guarantee improved performance and involve risk, including potential loss of principal. Past performance does not guarantee future results. The information provided is for educational and informational purposes only and does not constitute investment advice and it should not be relied on as such. It should not be considered a solicitation to buy or an offer to sell a security. It does not take into account any investor's particular investment objectives, strategies, tax status or investment horizon. All information has been obtained from sources believed to be reliable, but its accuracy is not guaranteed. There is no representation or warranty as to the current accuracy, reliability or completeness of, nor liability for, decisions based on such information and it should not be relied on as such.
About the Author – Tim Macarak CFP®
Tim Macarak is President & Head of Wealth Management at Member’s Wealth, a boutique wealth management firm that offers a comprehensive approach to serving individuals, families, business owners, and institutions. The firm’s goal is to preserve and grow its clients’ wealth to endure overtime, while thoughtfully evolving its strategy to suit an ever-changing world. With over 20 years of wealth management experience, Tim and the Members' Wealth team thrive on bringing clarity and confidence to clients' unique situations. He believes everyone needs sound financial advice from someone whose interests are aligned with theirs and is determined to put service before all else.
Tim is a CERTIFIED FINANCIAL PLANNER® Professional. Outside work, he enjoys spending time with his wife and kids, Skiing, Coaching, and Traveling. To learn more about Tim, connect with him on LinkedIn.
To get in touch with the Members’ Wealth team today, I invite you to email info@memberswealthllc.com or call (267) 367-5453.
You can learn more about how we serve our clients by tapping the button below.
Investment advisory services are offered through Members’ Wealth, LLC., a Registered Investment Advisory Firm.
Registration with the SEC does not imply a certain level of skill or training. We are an independent advisory firm helping individuals achieve their financial needs and goals
Members’ Wealth does not provide legal, accounting or tax advice. Please consult your tax or legal advisors before taking any action that may have tax consequences.
This commentary reflects the personal opinions, viewpoints and analyses of the Members’ Wealth, LLC employees providing such comments, and should not be regarded as a description of advisory services provided by Members’ Wealth, LLC or performance returns of any Members’ Wealth, LLC client. The views reflected in the commentary are subject to change at any time without notice. Nothing in this commentary constitutes investment advice, performance data or any recommendation that any particular security, portfolio of securities, transaction or investment strategy is suitable for any specific person. Any mention of a particular security and related performance data is not a recommendation to buy or sell that security. Members’ Wealth, LLC manages its clients’ accounts using a variety of investment techniques and strategies, which are not necessarily discussed in the commentary. Investments in securities involve the risk of loss. Past performance is no guarantee of future results
Copyright © 2023 Members' Wealth LLC